Appointment

Mortgage for Expats

Expat Mortgage in the Netherlands

An expat mortgage in the Netherlands is a regular Dutch home loan (a hypotheek) taken out by an international resident; the conditions are the same as for Dutch buyers, with a few extra requirements around your BSN, residence status and income.

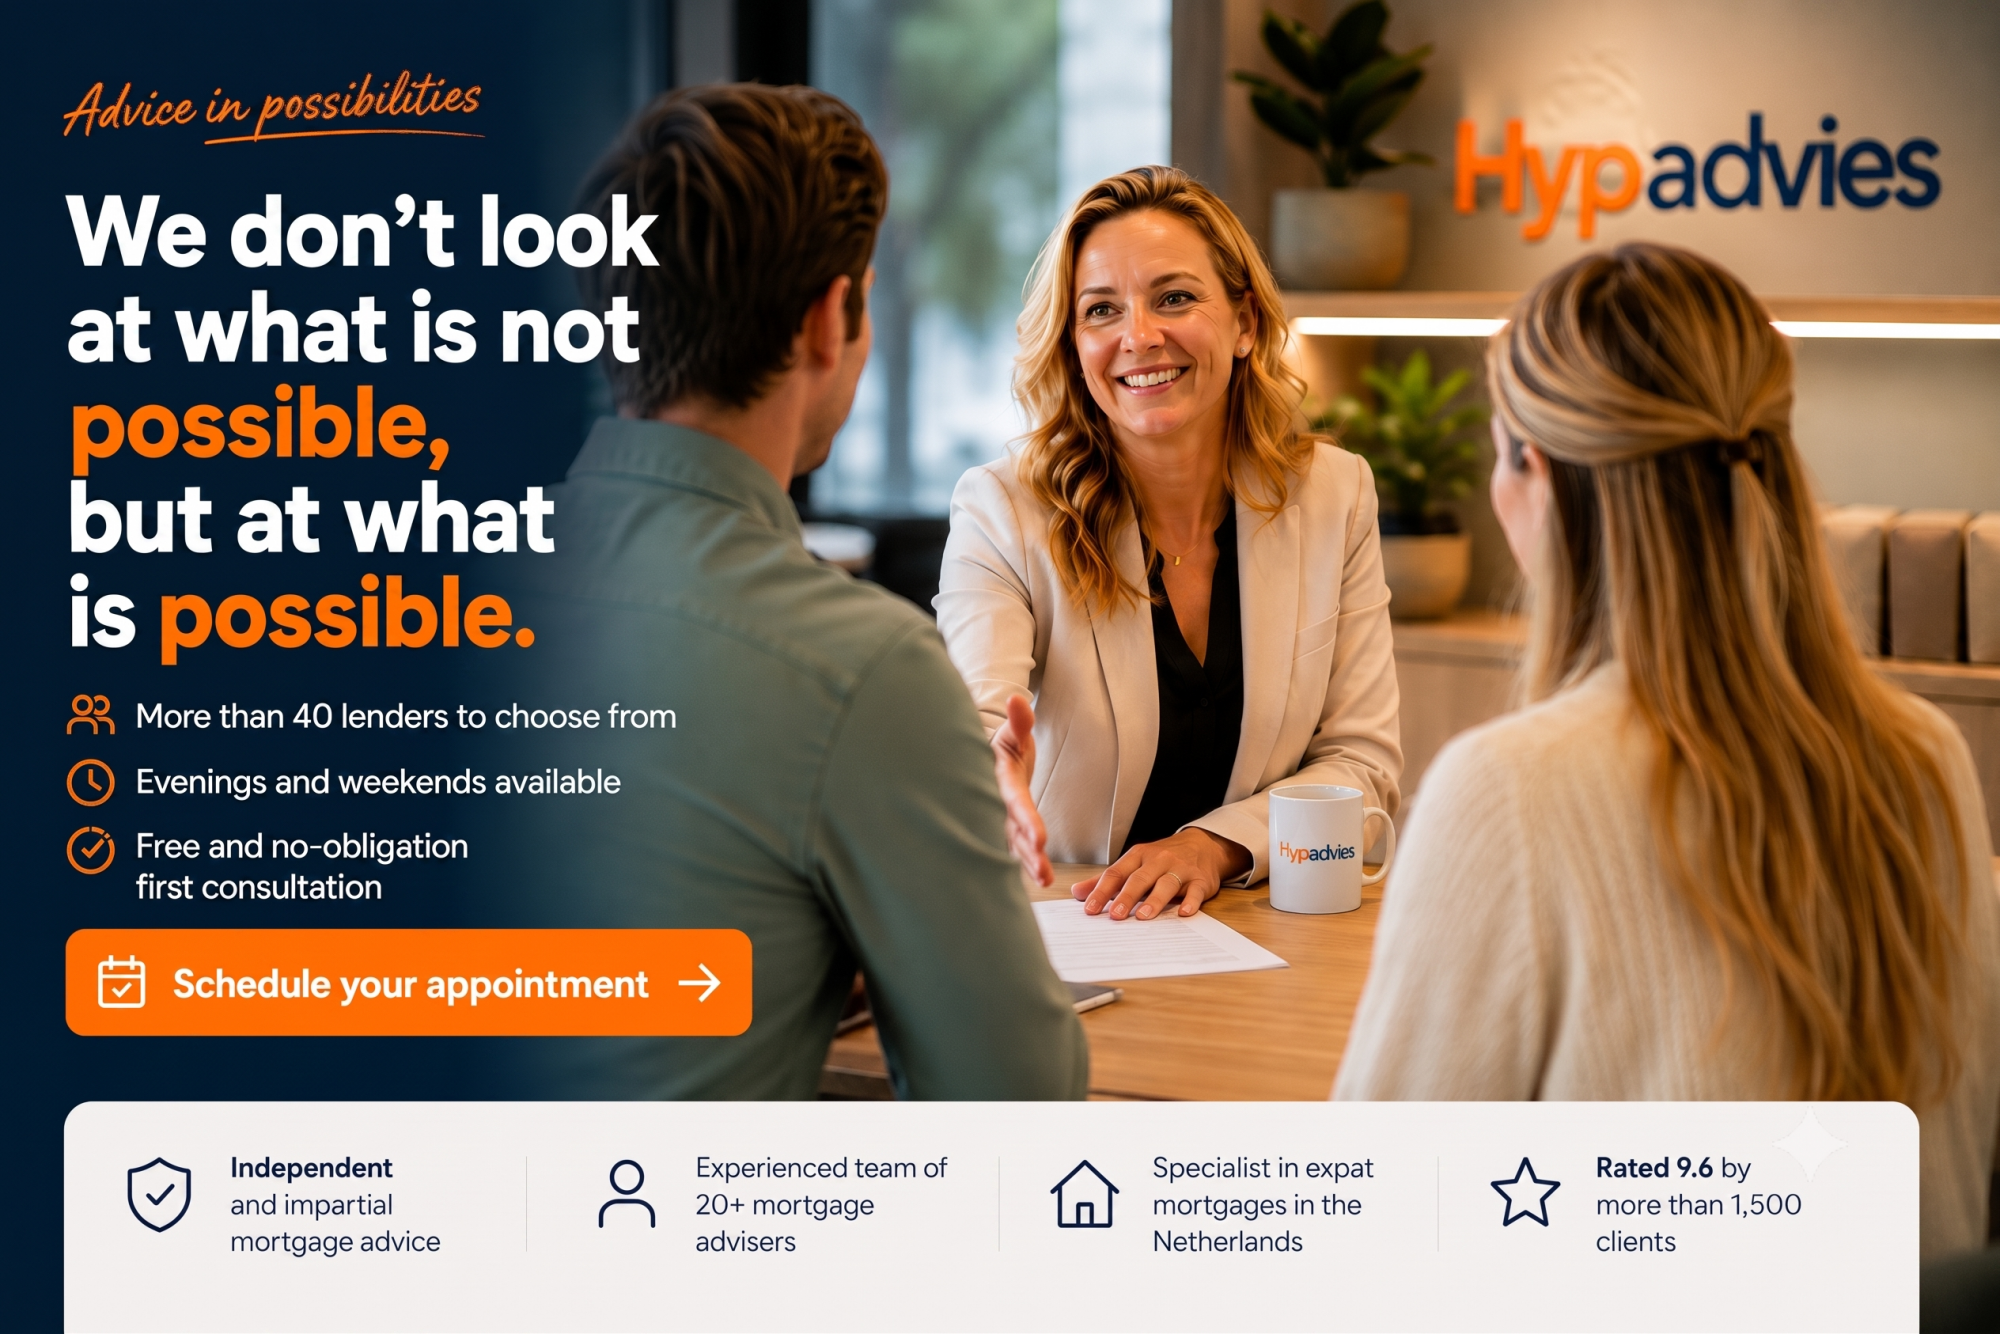
In short:  You do not need Dutch nationality to buy a home here. You do need a BSN, and often a residence permit if you are from outside the EU. Hypadvies is independent, compares more than 40 lenders, and advises you in English. The first meeting is free and without obligation.

Buying your first home in a new country is a big step, especially when the mortgage system works differently from what you know. At Hypadvies we guide internationals through the whole process in plain English, from your first calculation to signing at the notary. We are fully independent, so our advice serves you and not a single bank.

Checklist for a Complete Financial File

Do you want to enter the mortgage advice meeting with an advantage? 📄 Download this form and fill it out. Once done, email it back to info@hypadvies.nl, and we'll review it for you in advance. 📧👍
Mortgage Advice

Can expats get a mortgage in the Netherlands?

Yes. Internationals can buy a home in the Netherlands and apply for the same mortgage as Dutch residents. There is no separate expat product with different rates; you apply for a normal Dutch hypotheek. What differs is the paperwork the lender asks for, and that depends on where you are from and your residence status.

  • EU or EEA citizens: you are treated much like a Dutch applicant. You mainly need a BSN and proof of stable income.
  • Non-EU citizens: you usually also need a valid residence permit, and the lender will want to see that it can be extended.
  • Self-employed and freelancers: possible, but lenders look at your figures over a longer period. We know which lenders are flexible here.

The 30% ruling and your borrowing capacity

If you receive the 30% ruling, part of your salary is paid tax-free. This affects how lenders view your income. Some lenders count the full gross salary, others look only at the taxable part. Because we compare more than 40 lenders, we can point you to the ones that treat the 30% ruling in your favour, which can meaningfully change how much you are able to borrow.

What you need to apply

Every situation is different, but most applications need the following:

  • A BSN (citizen service number).
  • A valid residence permit if you are from outside the EU or EEA.
  • Proof of income: recent payslips, or annual figures if you are self-employed.
  • An employer statement or a permanent contract, where relevant.
  • An overview of your savings and any existing loans.

Not sure whether your situation qualifies? That is exactly what the free first meeting is for.

Fixed or variable interest?

Dutch mortgages come with either a fixed or a variable interest rate. The right choice depends on how much certainty you want in your monthly payments.

Fixed rate

Variable rate

Monthly payment

Stays the same for the fixed period

Can rise or fall with the market

Certainty

High: you know what you pay

Lower: depends on rate changes

Best for

Peace of mind, long-term planning

Flexibility, short horizon

The Dutch mortgage process, step by step

Knowing the order of steps takes a lot of the stress out of buying. This is how it usually goes:

  • 1. Know your budget. We calculate what you can realistically borrow based on your income and situation.
  • 2. Find a home. Most people search on Funda. Some agents run viewings aimed at internationals.
  • 3. Make an offer. The market moves fast, so a clear bidding strategy matters.
  • 4. Arrange the mortgage. Once your offer is accepted, we compare lenders and lock in your terms. Acting quickly protects your financing deadline.
  • 5. Sign at the notary. You sign the deed and the mortgage certificate, and the home is yours.

NHG for expats

Expats can take out a mortgage with or without the National Mortgage Guarantee (NHG). NHG can give you a lower interest rate and extra protection if your circumstances change. Whether it fits depends on the purchase price and your plans, and we walk you through it during your advice meeting.

Why internationals choose Hypadvies

  • Independent: we compare more than 40 lenders, so the advice is in your interest, not a bank's.
  • Advice in English: our advisors guide you clearly, without confusing jargon.
  • Local and reachable: offices across Noord-Brabant and the option of a webcam meeting if that suits you better.
  • A free first meeting: you find out where you stand before you commit to anything.

Ready to find out what is possible for you? Book a free, no-obligation first meeting and we will guide you toward your Dutch home.


Appointment

Frequently asked questions

Can I get a mortgage in the Netherlands as an expat?

Yes. You apply for the same mortgage as Dutch residents. You will usually need a BSN, and a residence permit if you are from outside the EU or EEA. Your income and contract type also play a role.

Is there a special expat mortgage with different rates?

No. There is no separate expat product. You apply for a normal Dutch hypotheek at the same rates as Dutch buyers. Only the required documents differ.

Does the 30% ruling affect how much I can borrow?

It can. Some lenders count your full gross salary and others only the taxable part. Because we compare more than 40 lenders, we can find the ones that treat the 30% ruling most favourably for you.

Do I need a permanent contract to get a mortgage?

Not always. A permanent contract makes it simpler, but there are options for temporary contracts and self-employed applicants. An employer statement can help, and some lenders are more flexible than others.

Is the advice really in English?

Yes. Our advisors guide expats in English through every step, from the first calculation to signing at the notary.

What does the first meeting cost?

The first meeting is free and without obligation. You leave knowing where you stand before you decide anything.

Appointment